Labrador Insurance Premiums by Age
It's a tough pill to swallow when you realize that the cost of giving your beloved Labrador the best possible care seems to climb right along with their age. Many of us find ourselves wondering if pet insurance is truly worth it, especially as those premium notices start looking a little steeper with each passing year. This comprehensive guide is here to demystify how your Labrador's age impacts pet insurance premiums, helping you understand what to expect and how to make informed decisions for their lifelong health.
The Basics of Labrador Pet Insurance and Age
Navigating the world of pet insurance can feel like trying to solve a complex puzzle, especially when you're deeply invested in your Labrador's well-being. One of the biggest pieces of that puzzle, and often the most confusing, is how age plays a pivotal role in the cost you pay for coverage. It’s not just a number on a birthday cake; it's a significant factor in how insurance companies assess risk.
Why Age Matters So Much for Premiums
Let's face it, just like with people, older dogs tend to have more health issues. As our Labradors mature, the likelihood of them developing conditions like arthritis, diabetes, or even cancer increases. Insurance companies operate on risk assessment. A young, healthy Labrador puppy represents a lower immediate risk of high-cost vet visits compared to a senior Labrador who might be experiencing the aches and pains of old age, or developing a chronic illness. This isn't a judgment on your furry friend; it's a cold, hard actuarial fact. Therefore, insurers adjust premiums to reflect this elevated risk. They're trying to balance the potential payout for claims against the income from premiums.
It's also about what's already happened. When you insure a young puppy, you're getting ahead of most potential health problems. By the time your Labrador reaches their golden years, they might have a history of various ailments. Many insurance policies have clauses about pre-existing conditions, which means anything diagnosed before or during a waiting period typically won't be covered. This makes insuring an older dog more challenging and often more expensive, as they may already have conditions that are excluded, leading to higher premiums for the remaining potential issues. The younger you enroll your Labrador, the better chance you have of getting comprehensive coverage before those conditions manifest.
Understanding Different Types of Policies
Not all pet insurance policies are created equal, and understanding the distinctions is crucial, especially as your Labrador ages and their needs change. Generally, you'll encounter a few main types of coverage, each with its own approach to what it covers and how that impacts premiums across different age groups. The most common is the accident and illness policy, which is often what people mean when they talk about pet insurance. This covers unexpected injuries, like a torn cruciate ligament from an enthusiastic run, or sudden illnesses, such as a severe ear infection or an unexpected diagnosis of something more serious like diabetes. These are the big-ticket items that can truly rack up vet bills, making this type of policy a lifeline for many Labrador owners facing Labrador Emergency Vet Bills that could otherwise derail their finances.
Then there are accident-only policies, which are generally much cheaper, but as the name suggests, they only cover injuries from accidents. While useful for rambunctious young Labradors prone to mishaps, they offer no protection against the illnesses that become more prevalent with age. Finally, some providers offer wellness plans or riders that can be added to accident and illness policies. These cover routine care like vaccinations, annual check-ups, and sometimes even dental cleanings. While they can help manage predictable costs, they typically don't count towards the "insurance" aspect of covering unexpected major expenses. Remember, a brand like Healthy Paws, for example, focuses on accident and illness coverage, which is where the real financial relief often comes in for serious, unexpected events. When considering options, always dive deep into what each policy explicitly covers and excludes, as these details become even more critical when looking at Pre-Existing Conditions on a Labrador Policy.
How Premiums Evolve from Puppyhood to Senior Years
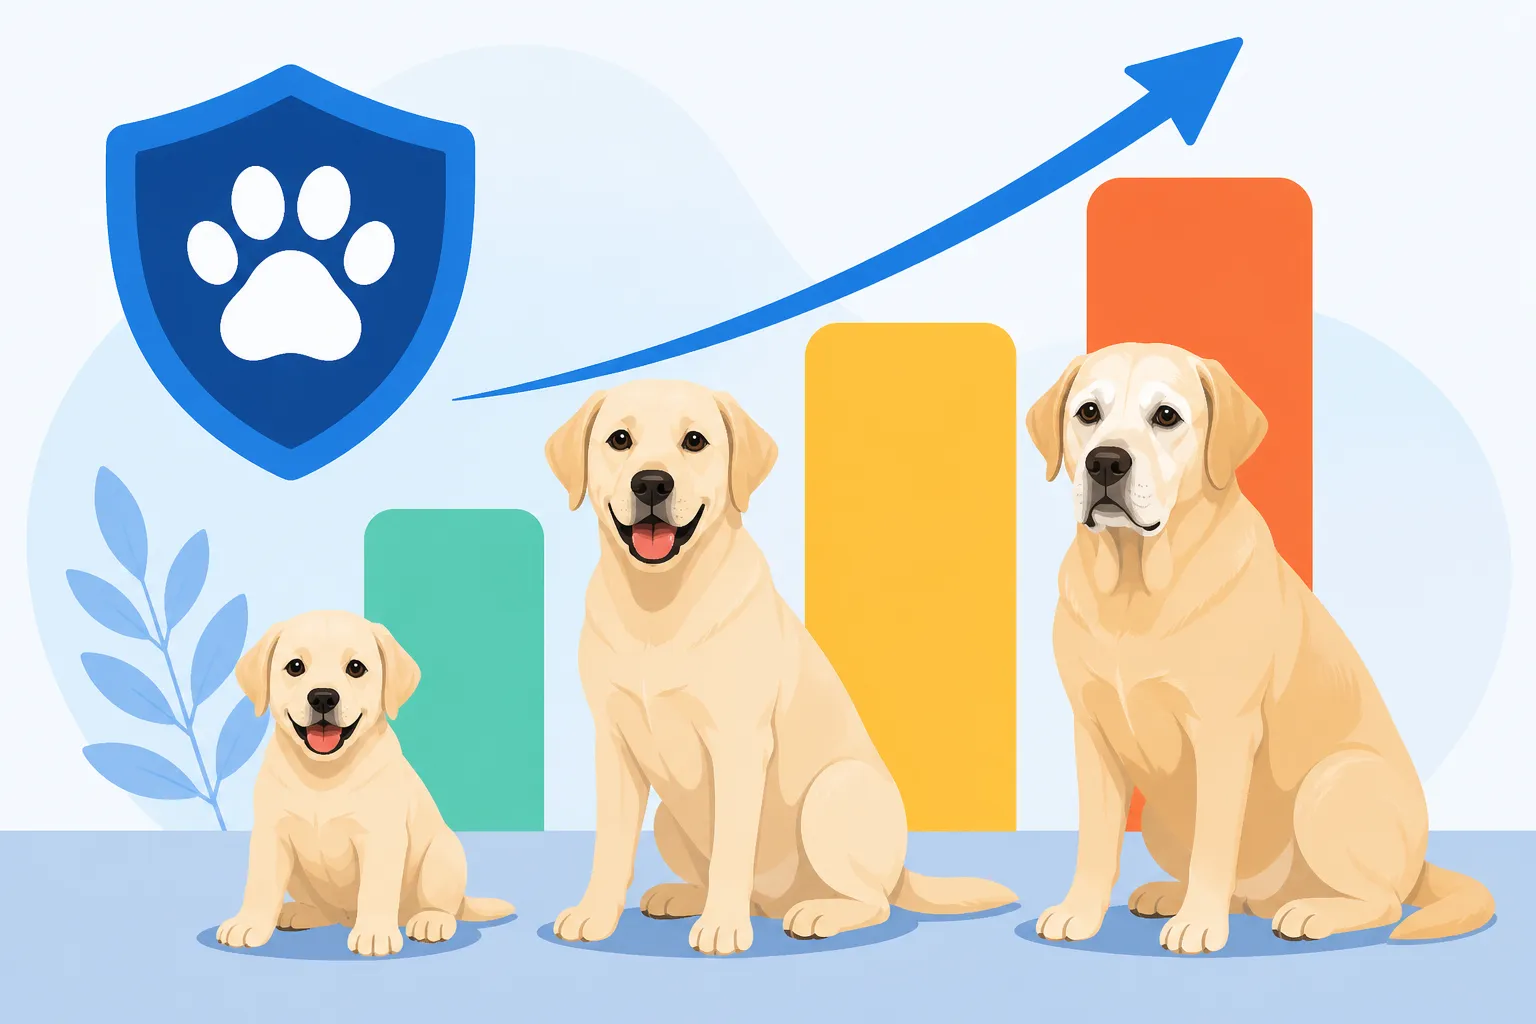
Watching your Labrador grow from a clumsy, cuddly puppy into a distinguished senior companion is one of life's greatest joys. However, this journey also comes with changing financial considerations, particularly when it comes to pet insurance. Understanding the typical premium trajectory can help you plan and avoid surprises.
Puppy Premiums: Early Days and What to Expect
When you first bring home that adorable Labrador puppy, pet insurance premiums are often at their lowest. This is largely because puppies are generally considered to be in their prime health, with a lower incidence of chronic conditions or major illnesses. However, this isn't to say puppies are cheap to insure. They are bundles of boundless energy, curiosity, and sometimes, a little bit of mischief, which means they're prone to accidents. Think about all those things they might chew and swallow, or the tumbles they might take learning to navigate the world. These unexpected events are precisely what an accident portion of a policy would cover.
Moreover, puppyhood is a critical time for foundational health. Ensuring your pup gets all their vaccinations and regular check-ups is vital. While these routine visits often aren't covered by standard accident/illness policies, it’s worth noting that some insurers, or pet product retailers like Chewy, might offer resources or even partnerships that could make early care more accessible. The goal during puppyhood is to lock in coverage before any conditions develop that could later be deemed pre-existing. For instance, if your puppy is diagnosed with a congenital condition like a heart murmur or an early sign of Labrador Hip and Elbow Dysplasia, these could impact future coverage if not insured from the outset. Early enrollment ensures that any issues that arise later in life, and aren't pre-existing, will be eligible for coverage, saving you significant money down the line.
Adult Labradors: The Middle Ground
As your Labrador transitions from a rambunctious puppy to a mature adult, typically between one and seven years old, their insurance premiums will likely see a gradual increase. This phase often represents a sweet spot where your dog is past the riskiest "puppy antics" but hasn't yet reached the age where chronic health issues become commonplace. Their immune systems are robust, and they're generally at their peak physical condition, especially if you're mindful about Keeping a Labrador at a Healthy Weight. However, this doesn't mean they're immune to problems.
During these middle years, Labradors are still highly active and can be prone to injuries like cruciate ligament tears or other orthopedic issues. Moreover, some genetic conditions or breed-specific ailments, such as certain types of allergies or early-onset Labrador Eye Conditions and Vision Loss, might start to manifest. Insurance companies will factor in the increasing likelihood of these conditions as your Labrador accumulates more years. The yearly increases might feel small at first, perhaps just a few dollars a month, but they are a consistent upward trend reflecting the incremental rise in health risks. This is also the period where proactive health management, including regular vet check-ups and a high-quality diet (perhaps even considering fresh food options from services like Ollie if your budget allows), can make a big difference in maintaining their health and potentially mitigating some of the steepest premium hikes later on.
Senior Labradors: The Peak of Premiums
Once your Labrador reaches their senior years, generally around seven or eight years old and beyond, you can expect to see the most significant jumps in pet insurance premiums. This is the stage where the statistics catch up, and the risk of age-related diseases escalates dramatically. Arthritis, kidney disease, heart conditions, diabetes, and various forms of Cancers Labrador Retrievers Get Most become far more common. Managing Caring for a Senior Labrador often involves more frequent vet visits, specialized diets, ongoing medications, and potentially expensive diagnostics or treatments.
Insurance companies are acutely aware of these increased risks. They are essentially balancing the higher probability of costly claims with the monthly premiums. It's a difficult reality to face, as this is precisely when you want the most robust financial safety net for your aging companion. For many Labrador owners, these rising premiums can feel like a punch to the gut, especially when coupled with the emotional stress of watching their beloved dog age. It's during this time that you might find yourself reviewing your policy annually, perhaps adjusting your deductible or reimbursement level to try and keep the monthly cost manageable, while still ensuring coverage for major, unforeseen events. Understanding these escalating costs is a key part of planning for the final stages of your Labrador's Labrador Lifespan and What Changes It.
Factors Beyond Age That Influence Your Labrador's Premium
While age is undeniably a colossal factor in determining pet insurance premiums, it's far from the only variable at play. Several other elements combine to create the final figure you see on your monthly statement, and understanding these can empower you to make more informed choices for your Labrador.
Breed-Specific Conditions and Genetic Predispositions
The very fact that you own a Labrador Retriever significantly influences your insurance premium. While Labs are known for being generally robust, they are also predisposed to certain health conditions that are common within the breed. For instance, Labrador Hip and Elbow Dysplasia is a well-documented concern, as are certain eye conditions like Progressive Retinal Atrophy. Some Labradors are also genetically prone to obesity due to The POMC Gene and Labrador Appetite, which can lead to a host of secondary health issues. Insurance companies factor these breed-specific risks into their pricing models.
A Labrador might be seen as a higher risk for orthopedic claims compared to, say, a tiny toy breed with fewer structural issues. Similarly, if your Labrador comes from a line known for specific genetic health problems, even with proper Health Clearances a Labrador Breeder Must Show, the underlying genetic predisposition can still play a role in how insurers assess their risk profile. This isn't about blaming the breed; it's simply a reflection of veterinary data that shows certain conditions are more prevalent in Labradors. Some policies might even offer discounts if your dog has undergone Genetic Panels Worth Running on a Labrador and tested clear for certain conditions, while others might load premiums if there's a known family history of significant issues.
Location, Deductibles, and Reimbursement Levels
Where you live can have a surprising impact on your pet insurance premiums. Veterinary costs vary dramatically by geographic region, mirroring the cost of living and operating a business. A vet visit in a major metropolitan area like Los Angeles or New York City, for instance, will almost certainly be more expensive than the same procedure in a rural town in Kansas. Since insurance companies pay out a percentage of these vet bills, they adjust premiums based on the average veterinary costs in your specific zip code. If you move, don't be surprised if your premium changes to reflect the new local vet rates.
Beyond location, two key policy elements – deductibles and reimbursement levels – allow you to customize your premium. Your deductible is the amount you pay out of pocket before your insurance coverage kicks in each policy year. A higher deductible means a lower monthly premium, but you'll pay more upfront if your Labrador needs care. Conversely, a lower deductible leads to a higher monthly premium. Reimbursement level refers to the percentage of the eligible vet bill that the insurance company will pay after your deductible is met, typically ranging from 70% to 90%. Opting for a lower reimbursement level (e.g., 70% instead of 90%) will also result in a lower premium. It's a balancing act: you save on monthly premiums by taking on more financial risk yourself, or you pay more monthly for a larger safety net.
The Impact of Wellness Plans and Riders
While often offered alongside traditional pet insurance, wellness plans and riders function a bit differently and can influence your overall pet care budget and how you perceive your "premium" cost. A wellness plan, sometimes referred to as routine care coverage, is designed to cover predictable, non-emergency expenses. These include things like annual check-ups, vaccinations (which are critical during your Labrador Puppy Vaccination Schedule), parasite prevention, and sometimes even spay/neuter surgery. They are essentially pre-paid packages for services you know your Labrador will need, rather than insurance against unforeseen events.
Adding a wellness rider to your accident and illness policy will undoubtedly increase your total monthly payment. While it makes your "premium" higher, it can help spread out the cost of routine care, preventing large lump sums for things like annual exams. However, it's crucial to evaluate if the cost of the wellness plan actually saves you money compared to simply paying for these services out of pocket. For some, the convenience and budgeting aspect are worth the extra monthly cost. For others, particularly those on a tighter budget, it might make more sense to pay for routine care directly and keep their core accident and illness premium as low as possible, focusing their insurance dollars on truly catastrophic events. Always run the numbers to see if the plan truly benefits your specific financial situation.
Strategies for Managing Rising Labrador Insurance Costs
It's natural to feel a pinch as your Labrador's insurance premiums rise, especially as they enter their senior years. The good news is that you're not powerless. There are proactive steps you can take to manage these escalating costs while still ensuring your beloved companion receives the care they deserve.
Comparing Providers and Getting Multiple Quotes
One of the most effective ways to manage increasing insurance costs is to shop around, regularly. The pet insurance market is competitive, and premiums can vary significantly between providers for the exact same coverage. What might have been the best deal for your young Labrador five years ago might no longer be the most cost-effective option today. It's worth setting aside time each year, perhaps around your Labrador's birthday or policy renewal date, to gather multiple quotes. Don't be afraid to reach out to different companies. For example, while Healthy Paws is a well-known provider, you might find competitive rates from others.
When comparing, ensure you're looking at apples to apples. Compare policies with similar deductibles, reimbursement percentages, and annual maximums. Also, pay close attention to waiting periods, especially if you're switching providers with an older Labrador; you don't want to inadvertently create a gap in coverage or have a new illness suddenly be deemed pre-existing. Utilize online comparison tools, or even contact pet product retailers like Chewy, who sometimes partner with multiple insurance carriers and can help you compare plans side-by-side. This due diligence can potentially save you hundreds of dollars annually, especially as your Labrador Arthritis in Middle Age starts to become a concern.
Adjusting Coverage to Fit Your Budget
Sometimes, even with comparison shopping, the ideal, comprehensive policy can still feel out of reach, particularly as your Labrador ages and premiums peak. In these situations, adjusting your coverage levels can be a pragmatic way to keep insurance affordable, even if it means accepting a bit more financial risk yourself. This often involves playing with your deductible and reimbursement percentage. As discussed earlier, opting for a higher deductible will lower your monthly premium. For example, moving from a $250 deductible to a $500 or even $1,000 deductible could significantly reduce your monthly payments. You'd be responsible for more upfront if a claim arises, but you'd save money every month you don't file one.
Similarly, lowering your reimbursement level from, say, 90% to 80% or 70% will also reduce your premium. This means the insurance company covers less of the bill, and you cover more. While not ideal, it can be a necessary compromise to maintain some form of coverage, especially for major, catastrophic events that could lead to Cost of Hip Surgery for a Labrador Retriever or cancer treatments. It’s about finding a balance between what you can comfortably pay monthly and what level of financial risk you're willing to absorb if your Labrador gets sick or injured.
Self-Insuring vs. Traditional Policies
The idea of "self-insuring" is a strategy many consider, especially for pet owners who are wary of rising premiums or feel that their healthy Labrador hasn't utilized their policy much. Self-insuring essentially means you commit to regularly setting aside money into a dedicated savings account specifically for your Labrador's potential veterinary expenses. Instead of paying monthly premiums to an insurance company, you pay yourself. This can be a very effective method for Setting Up an Emergency Fund for a Labrador.
The main benefit is that you retain full control over your money. If your Labrador stays healthy, that money remains yours, earning interest. However, the significant drawback is that you bear 100% of the financial risk. If your Labrador suddenly faces a major illness or accident with a bill running into thousands of dollars early in their life, you might not have accumulated enough savings to cover it. For a breed like the Labrador, prone to big, active-dog injuries and certain expensive conditions, this can be a huge gamble. Traditional insurance policies offer peace of mind by transferring that risk to the insurer. The best approach for you might be a hybrid: a moderate insurance policy for catastrophic events, combined with a dedicated savings fund for routine care and smaller, unexpected costs.
Common Misconceptions and Pitfalls to Avoid
The world of pet insurance is rife with nuances, and it's easy for even the most diligent Labrador owner to fall prey to common misunderstandings. Being aware of these pitfalls can save you from significant financial headaches and heartbreak down the line.
Believing Insurance Covers All Pre-Existing Conditions
This is perhaps the biggest and most common misconception in pet insurance: that once you have a policy, all future veterinary issues will be covered. Unfortunately, this is almost never the case when it comes to pre-existing conditions. A pre-existing condition is generally defined as any illness or injury that your Labrador showed symptoms of, or was diagnosed with, before your policy's start date or during its waiting period. This is true whether the condition was formally diagnosed by a vet or merely noted in your pet's medical records (e.g., "limping last month").
For example, if your Labrador had a history of Labrador Ear Infections and Swimming before you got insurance, future ear infections related to that chronic issue might be excluded from coverage. This is why getting insurance when your Labrador is a young, healthy puppy is so crucial. The longer you wait, the more likely your dog is to develop minor issues that could become pre-existing exclusions later. Once a condition is flagged as pre-existing, it generally won't be covered by that policy, and if you switch providers, it will likely still be considered pre-existing by the new company too. Always read the fine print regarding Pre-Existing Conditions on a Labrador Policy and clarify any concerns with the insurer before committing.
Waiting Too Long to Get Coverage
The temptation to put off getting pet insurance is understandable. Your Labrador is young, healthy, and full of vigor, so why spend money on something you might not need right away? This "wait and see" approach is another significant pitfall, and one that often proves to be very costly in the long run. As discussed, the younger your Labrador is when you enroll them, the lower your premiums will typically be, and more importantly, the less likely they are to have developed any pre-existing conditions that will later be excluded.
Think about it: puppies are curious. They explore with their mouths, they tumble, they grow rapidly which can sometimes lead to transient lameness like Panosteitis in a Growing Labrador. While many of these are minor, if a more serious issue like a congenital heart defect or early signs of joint issues manifest, and you don't have insurance, you're either stuck paying out of pocket or waiting to get coverage that will then exclude that specific problem. By waiting, you risk major health issues appearing that will not only incur huge vet bills but also make future insurance premiums higher and coverage less comprehensive. It’s always best to insure your Labrador as early as possible to maximize your coverage and minimize exclusions, even if it feels like an unnecessary expense at the time.
Making the Best Financial Choice for Your Labrador
Ultimately, deciding on pet insurance for your Labrador, and how to manage its costs, is a deeply personal and financial decision. There's no single right answer, but by carefully weighing the pros and cons, you can make a choice that brings you peace of mind and ensures your furry family member gets the best care.
Weighing the Long-Term Benefits Against Annual Costs
It's easy to look at the annual cost of pet insurance and feel like it's a significant drain on your budget, especially if your Labrador has had a year free of major health issues. However, it's essential to shift your perspective from short-term outlay to long-term protection. For a breed known for its love of life and activity, and with a respectable Median Labrador Lifespan in Veterinary Records, you're looking at potentially a decade or more of veterinary care. A single major accident, like a broken bone, or an illness, such as a cancer diagnosis, can easily cost thousands of dollars – far exceeding years of premiums.
Consider the potential for Labrador Obesity and the Years It Costs, or the ongoing management for conditions like diabetes or severe allergies, which can add up to substantial expenses over time. Pet insurance acts as a financial buffer against these unpredictable, often astronomical, costs. It allows you to make medical decisions based on what's best for your Labrador, rather than being constrained by your wallet. The long-term benefit isn't just about money; it's about the emotional peace of mind knowing you can say "yes" to necessary treatments without facing financial ruin. For many, this security is well worth the annual investment.
When to Consider Switching Providers
Loyalty is a wonderful trait, especially when it comes to companies we trust. However, in the realm of pet insurance, staying with the same provider year after year without review can sometimes mean you're missing out on better deals or more suitable coverage. Your Labrador's needs evolve, and so does the market. As mentioned earlier, conducting an annual review of your policy and comparing it with other providers is a wise practice.
You might find that a different company offers better rates for Senior Labrador Medication Costs, or has different policies regarding what they consider pre-existing as your Labrador ages. Some companies might specialize in specific breeds or age groups, offering more competitive plans for a senior Labrador than the one you started with when they were a puppy. For instance, you could find a more favorable plan from another insurer than your current one by checking out what different providers like Healthy Paws are offering. Before switching, though, be incredibly diligent. Understand the new policy's waiting periods, and critically, how they define and handle any conditions your Labrador has already been diagnosed with. You don't want to switch only to find a crucial existing condition is now excluded by your new provider.
| Labrador Age Category | Typical Premium Trend (Monthly Estimate, example) | Common Health Considerations (Impacting Premium) |
|---|---|---|
| Puppy (0-1 year) | Lowest ($30-$50) | Accidents, vaccinations (if wellness added), congenital issues, early joint assessment. |
| Adult (1-7 years) | Moderate ($40-$70) | Orthopedic injuries, allergies, dental issues, early onset of chronic conditions. |
| Senior (7+ years) | Highest ($60-$100+) | Arthritis, cancer, organ disease, diabetes, cognitive decline, multiple chronic conditions. |
Note: These premium estimates are general examples and can vary widely based on location, deductible, reimbursement level, specific breed line, and individual insurer.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, veterinary, or professional advice. Pet insurance premiums, coverage, and terms can vary significantly. Always consult with a qualified veterinarian for your Labrador's health needs and a licensed insurance professional to discuss specific policy options and determine the best fit for your individual circumstances.